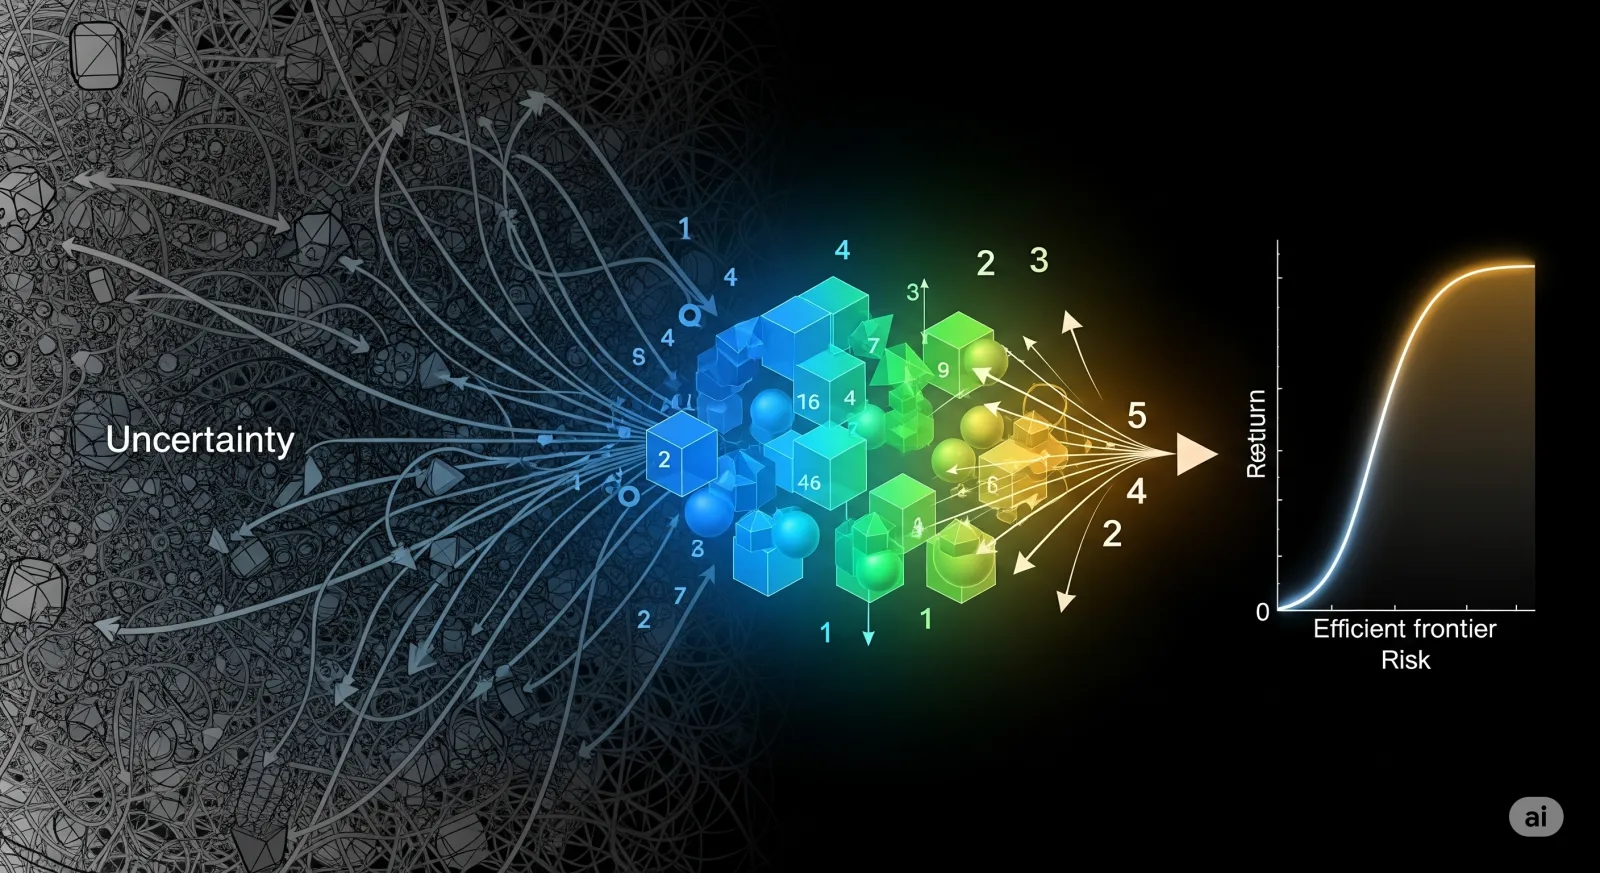
Causality Is Optional: Rethinking Portfolio Efficiency Through Predictive Lenses
A practical reading of why portfolio efficiency depends less on causal purity than on signal geometry: alignment, ranking, and calibration.
A practical reading of why portfolio efficiency depends less on causal purity than on signal geometry: alignment, ranking, and calibration.

A sharper reading of order-flow filtration: cleaning the visible book barely improves standing-book imbalance, but filtering the parent orders behind executed trades exposes a clearer directional signal.
A mechanism-first reading of how information geometry turns Lévy jump models into comparable, estimable, and diagnostically useful financial model spaces.

A mechanism-first look at Technical Indicator Networks, which turn classical trading indicators into trainable neural architectures without throwing interpretability into the usual black-box bonfire.

A mechanism-first reading of how Wasserstein QGANs may generate synthetic financial time series with distributional realism and partial temporal structure.

A mechanism-first reading of Lévy-driven option pricing when the market has no clean risk-free asset to lean on.

A comparison of analytical volatility calibration and signature-based rough-path models, showing where speed, structure, flexibility, and model risk actually trade off.

Bitcoin’s complexity is not just higher volatility; it is scale-dependent structure that changes how risk, forecasting, and model validation should be read.
MountainLion shows how multi-agent LLM systems can compress crypto research workflows, but its strongest value is interpretability and decision support rather than proven autonomous trading alpha.
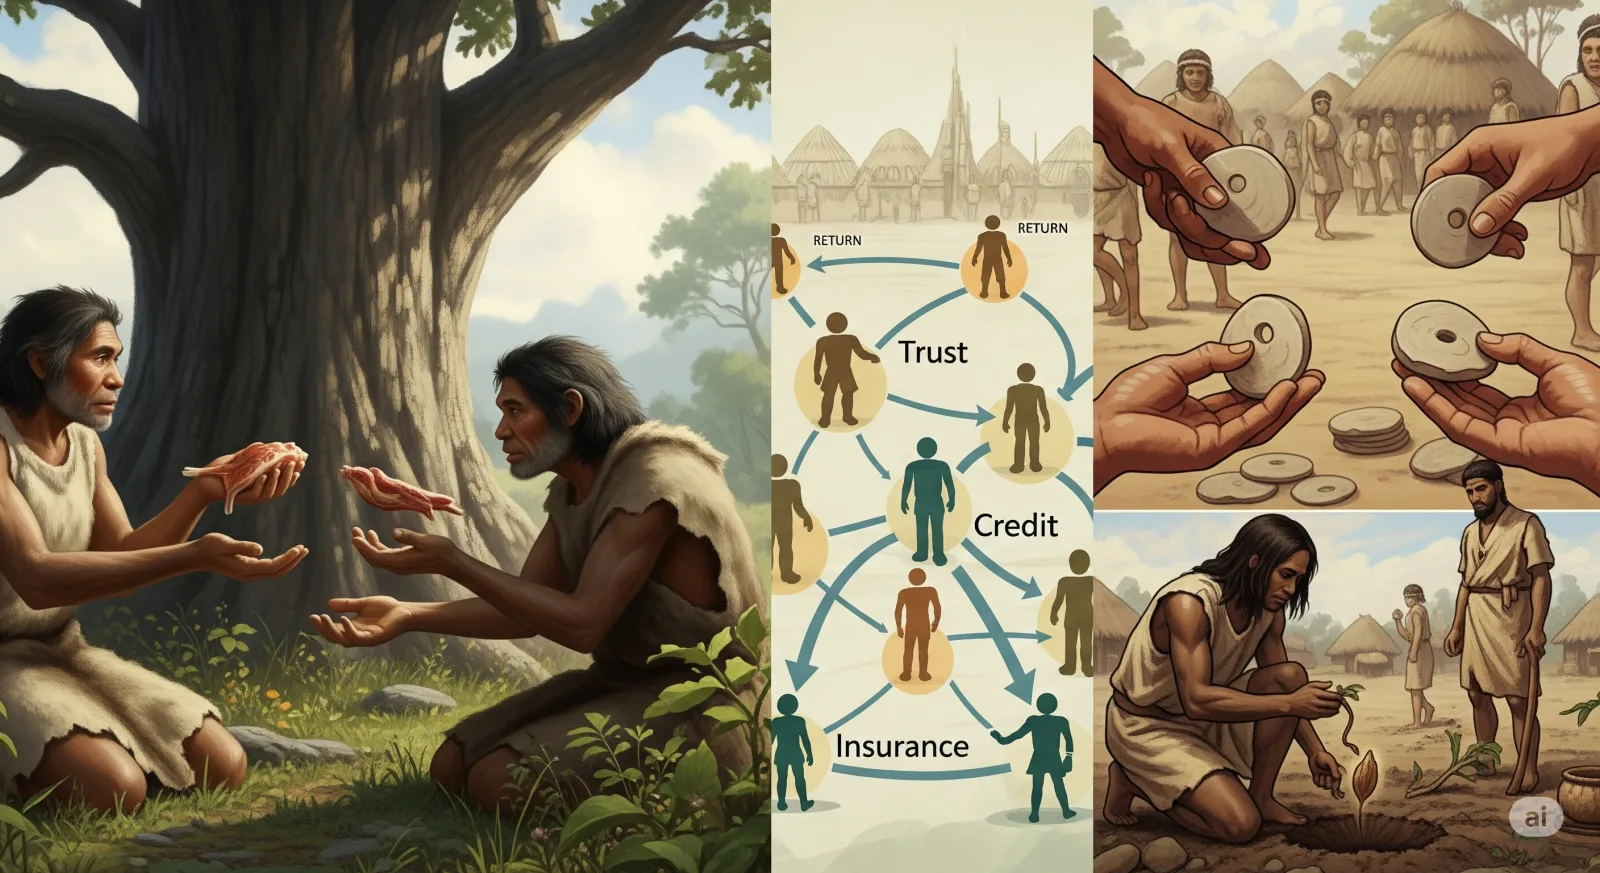
A mechanism-first reading of finance as extended reciprocity, with implications for AI-agent markets, decentralized trust, and simulation design.